Waiting On Biden’s Student Loan Forgiveness Cost Borrowers Up To 43%, NBER Finds
- Borrowers who expected forgiveness or another break extension reduced their loan payments by an average of $40 per month.
- Those same borrowers are 7.5% more likely to be seriously delinquent today.
- Wagering on a loan that never arrived can cost up to 43% of the borrower’s original loan balance.
Borrowers who believed in student loan payment break would continue to roll over (or that their debt would be completely forgiven) would lower their payments, spend more, and are now more likely to be delinquentaccording to a new National Bureau of Economic Research working paper.
Economists polled borrowers about their expectations during the 2022 break and forgiveness announcement, then correlated those responses with credit bureau data, employment and spending.
The key finding: Policy uncertainty alone has changed borrower behavior, and costs are still emerging student loan debt statistics today.
Why is it important?
Between March 2020 and 2023, the payment break was extended eight timesoften at the last minute after being framed as “final”. President Biden’s August 2022 Mass Pardon Plan Announced, Litigation Launched, and struck down by the Supreme Court in June 2023, but borrowers have already adjusted their finances as if relief were coming.
The study puts hard numbers on how much that whiplash costs. Borrowers who bet on relief that never arrived pay more interest, he fell behind more oftenand in some cases thousands of dollars worse. You can see in the chart below how many borrowers have been making payments over almost the last decade:
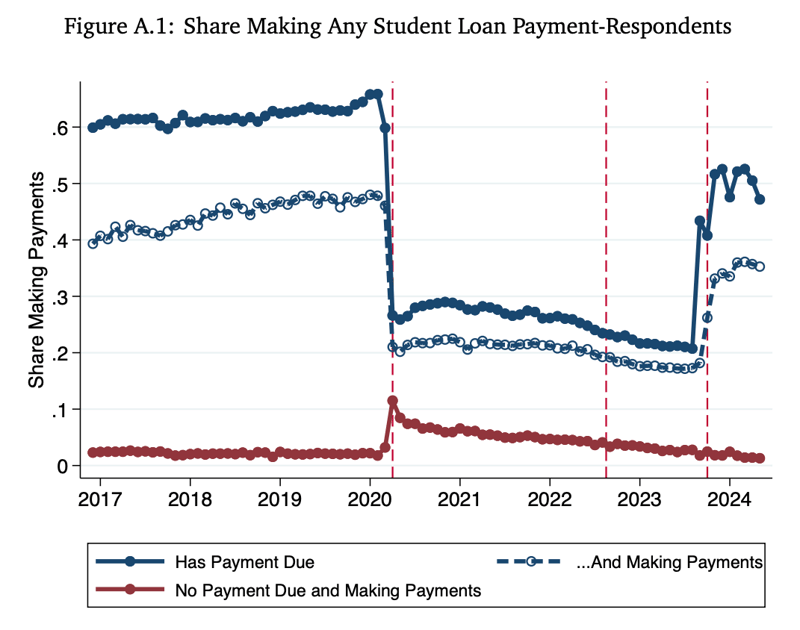
With the numbers
Borrowers who were optimistic about loan forgiveness reduced their student loan payments by $40 per month and increased their spending on non-durable goods by $100 per month, even payments were set to restart.
Borrowers who expected another break extension also reduced their payments by $40 per month and were 7.5% more likely to be delinquent for at least three months by May 2025, well after the resumption of payments.
The study’s authors found that losses from incorrect forgiveness beliefs can exceed 43% of a borrower’s initial loan balance.
On American Enterprise Institute notes that reduced payments made in anticipation of forgiveness are costing borrowers up to 7% of their balances in additional interest, equating to thousands of dollars in typical loan balance.
What the 43% loss figure really means for borrowers
That 43% figure does not mean that loan balances grew by 43% (although balances did).
Here’s the simple version: imagine you owe $100, and someone in charge keeps hinting that the debt can be written off. That way you will stop paying and spend your money elsewhere. Three costs accrue while you wait:
- Your debt continues to grow due to interest, so the $100 balance increases.
- When forgiveness never comes, you’re out repayment habit and more likely to miss payments, which will bring damage with a late payment like on destroyed credit score (which is especially very expensive).
- The money you spent while you waited went to choices you wouldn’t have made had you known the truth.
Economists add up all that damage (what they call the “welfare loss”) and compare it to the original loan. For borrowers who bet the hardest forgiveness that never camethe total damage can be worth more than 43% of the initial state. That is a worst-case estimate, not the experience of the average borrower.
If you want to focus only on the additional interest accrued, that cost is the number “up to 7%”. It is similar to estimates of $3,500 in additional interest costs for those who stayed in SAVE forbearance.
The bigger picture
“When policymakers announce policies that later face legal or political obstacles, households may adjust their spending, saving, borrowing, and repayment decisions in anticipation of benefits that may never arrive.“, write the authors of the study.
That pattern hasn’t gone away. The Department of Education partially continued involuntary collections in 2025 (incl salary garnishment and tax refund offset) afterwards he stopped them abruptly again in January 2026, with no firm timeline for the restart.
Borrowers who default while collection is pending continue to accrue interest and fees, meaning the balance will be higher each time foreclosure returns.
How does this connect
The study helps explain the wave of delinquency we’ve been tracking. Education Secretary Linda McMahon put it bluntly to senators 1 in 4 federal student loan borrowers are now delinquent or in default, New York Fed data showed 3.6 million borrowers newly defaultedwith credit scores dropping by an average of 91 points. Delinquent loan balances reached 179 billion dollars and are now set to be charged from the reduced treasury.
Research suggests that these numbers are not just about defaulting borrowers. Years of stop-and-start policies have taught many borrowers to expect that payments are optional or that forgiveness is inevitable, and getting back into repayment habits proves slow and expensive. For borrowers who are already in default, options like loan rehabilitation it can prevent the damage from getting worse.
The paper’s warning applies to the current administration as much as it did the last: Any open pause or vague “we’ll eventually resume collection” shapes borrower behavior now.
The Department of Education has already told borrowers yes expect repayment, not forgiveness – The study suggests that clear timelines and credible commitments cost less, for the government and lenders, than relief that may never arrive.
Don’t miss these other stories: