Using Personalized Lifespan Estimation For Retirement
There is a long-standing aphorism among financial planners about the difficulty of retirement planning: If the client can Only Tell me the exact day they will die, I will make them Perfect Pension plan. The truth is, no one knows when they will pass; While life insurance companies can be incredibly efficient at estimating the life expectancy of an entire population based on the law of large numbers, any customer is a sample size. That means most advisors simply plug a “reasonably conservative” estimate into their retirement planning software and plan from there.
In this guest postDr. K. Jeremy Ko of Shore Up Retirement Solutions explores how advisors typically estimate a retirement client’s life expectancy and the impact of developing more customized life expectancy estimates to better estimate how much clients need to save for retirement, how much they can safely spend in retirement, or the variability in when Social Security benefits begin.
A starting point is knowing how common it is for most advisors to simply use a standard conservative life expectancy estimate, with one recent analysis showing that nearly 90% of advisors simply use the age-90 or age-95 estimate already built into their financial planning software. Despite the fact that different demographics – from income to education to race – have materially different life expectancies, in many cases by 10-15+ years. This means, at the very least, advisors will benefit from looking at client-demographic-specific document charts beyond the standard population average.
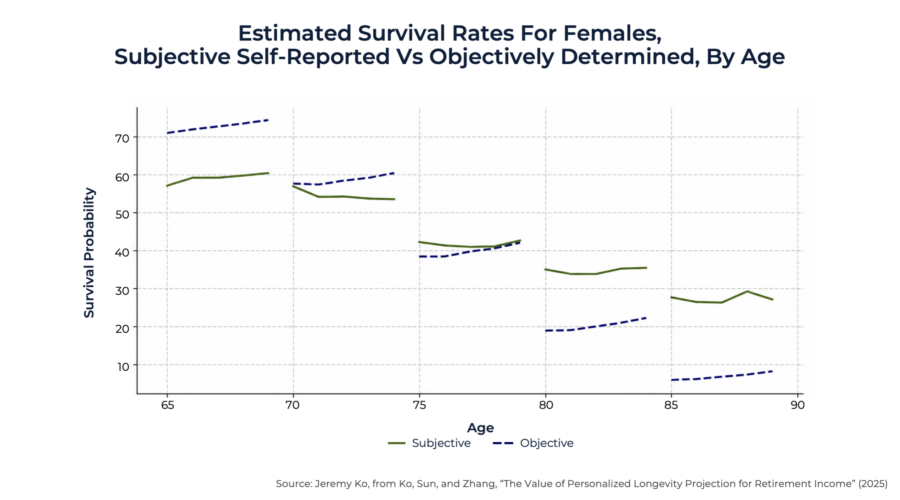
At the same time, many counselors may prefer to ask their clients what they are. His own The choice is life expectancy: Research shows that consumers also systematically misjudge their own life expectancy in a so-called “deception bias,” with younger individuals underestimating their life expectancy (ie, not realizing how long they will live in retirement), and older individuals tending to overestimate their life expectancy (ie, not realizing how short the years are). This is particularly problematic because these client misconceptions tend to bias plan advice toward retirement assumptions rather than being systematically more conservative.
So what is the alternative? Using emerging technology tools – calculators from the Association of Actuaries, Connecticut Goldenson University of Actuarial Sciences or the Northwestern Common Lifetime Calculator – to make more client-specific recommendations that take into account their personal income, education and health issues. The two identical clients can differ by up to 20 years in life expectancy based on selected health and other demographic factors, which can materially affect planning recommendations that may otherwise be overlooked.
Another benefit of the emerging crop of technology tools is that it can make the conversations with clients easier, as advisors can either walk through the questionnaire with clients together, or offer them the opportunity to do it on their own (if the clients are otherwise uncomfortable to talk about specific family or health factors that may impact their longevity) and simply use the results from the software output itself. Realizing that, because advisors still tend to be conservative – no client wants to see their money run out. rootEstimating Life Expectancy – Advisors may still default to more conservative longevity estimates (such as the 90th percentile life expectancy rather than using the 50th percentile median).
Ultimately, though, the bottom line is just knowing that life expectancy in retirement can vary; so true It depends significantly on individual health, demographics and other factors. Using only a broad-based, conservative estimate of a client’s life expectancy—assuming that all clients will live to age 90 or 95—results in inappropriate care for clients who are still not in good health, and recent medical advances actually look down The life expectancy of the most healthy customers. Finally, no life expectancy tool can accurately predict how long a client will live, but the more life expectancy estimates are tailored to the individual client and their retirement, the more accurate the recommendations can be, even if they are not perfect.
| And if you want to go deeper on this topic, directly from the author at Financial Advisor Technician Podcast . |